The Business Research Company’s Analysis of Edge Artificial Intelligence Chips Global Market Report 2026 – Market Size, Trends, And Forecast 2026-2035
LONDON, GREATER LONDON, UNITED KINGDOM, October 26, 2026 /EINPresswire.com/ — The edge artificial intelligence (AI) chips market is on track for remarkable growth in the coming years, fueled by rapid advancements in AI technology and the rising need for intelligent, low-latency processing at the edge. As AI becomes more integrated into everyday devices and industrial applications, this sector is emerging as a crucial area within the broader technology landscape. Let’s explore the market’s size, regional dynamics, key drivers, segments, leading companies, and competitive trends shaping its future.
Projected Market Size and Its Role Within the Larger AI Ecosystem
By 2030, the edge artificial intelligence chips market is expected to exceed $15 billion. This segment forms a small but significant part of the overall Artificial Intelligence market, which is forecasted to reach about $920 billion the same year. When viewed within the context of the entire Information Technology sector, projected to be worth $13,788 billion by 2030, edge AI chips will represent roughly 0.1% of the total market value.
Request A Free Sample Of The Edge Artificial Intelligence Chips Market Report
https://thebusinessresearchcompany.com/sample_request?id=69524750&type=smp&name=Edge%20Artificial%20Intelligence%20Chips%20Market%20Report%202026&utm_source=EINPresswire&utm_medium=Paid&utm_campaign=Oct_PR
North America’s Dominance in the Edge AI Chips Market by 2030
North America is set to lead the edge artificial intelligence chips market in 2030, with an estimated valuation of $4.8 billion. The market is predicted to grow from $2.2 billion in 2025 at a compound annual growth rate (CAGR) of 16%. This strong expansion is driven by the presence of top AI semiconductor firms and large-scale technology companies, increasing adoption of edge computing infrastructure, growing use of AI-powered industrial automation and connected devices, significant investments in next-gen semiconductor technology, and a high demand for low-latency AI processing in both enterprise and consumer sectors.
The United States as the Largest Country Market for Edge AI Chips
In 2030, the US will be the biggest individual country market for edge artificial intelligence chips, valued at $4.2 billion. Starting from $2.0 billion in 2025, the market is expected to grow at a CAGR of 16%. Key factors supporting this growth include rapid commercialization of edge AI technologies, enhanced integration of AI processors into autonomous systems and intelligent robotics, expanded use of AI in healthcare and industrial sectors, considerable R&D investments targeting advanced chip design, and ongoing innovation by domestic semiconductor companies to boost edge computing performance and energy efficiency.
Access The Detailed Edge Artificial Intelligence Chips Market Report Here
https://thebusinessresearchcompany.com/report/edge-artificial-intelligence-chips-global-market-report?utm_source=EINPresswire&utm_medium=Paid&utm_campaign=Oct_PR
Top Chip Segment in the Edge AI Chips Market for 2030
Among chip types, application-specific integrated circuits (ASICs) will be the largest segment, making up 42%—or $6 billion—of the total edge artificial intelligence chips market in 2030. The dominance of ASICs stems from growing demand for dedicated AI acceleration, superior energy efficiency in edge AI inference tasks, increasing use in autonomous vehicles and smart IoT devices, broader deployment of application-optimized processors in industrial settings, and continuous improvements in custom AI chip design that enable powerful edge computing performance.
Segment Overview by Device Type, Function, and Industry Use
The edge AI chips market is further divided by device type into consumer and enterprise devices. Functionally, it spans training and inference segments. Key end-use industries encompass automotive, manufacturing, healthcare, consumer electronics, and others, reflecting the broad applicability of edge AI technology across multiple sectors.
Expected Growth Rate and Market Expansion Drivers Through 2030
The market is forecasted to grow at a 17% CAGR leading up to 2030. Several critical factors will fuel this rapid expansion, including the increasing adoption of edge computing, rising consumer demand for smart devices equipped with AI capabilities, and the growing presence of autonomous vehicles and advanced driver assistance systems.
The Rising Trend of Edge Computing Adoption
Edge computing’s widening adoption is a primary catalyst for growth in the edge AI chips market. Organizations are processing data near its point of origin to reduce latency, optimize operations, and enable swift decision-making. Edge AI chips provide necessary local computing power for complex AI tasks without depending on continuous cloud access. Sectors like manufacturing, healthcare, retail, and telecommunications are deploying intelligent edge infrastructure more extensively, which in turn is boosting demand for these specialized chips. This shift towards distributed AI processing is expected to contribute roughly 1.5% annual growth to the market.
Growing Market Demand for Smart Consumer Devices
The surge in demand for smart consumer electronics also plays a vital role in market growth. Devices such as smartphones, wearables, smart home systems, and intelligent cameras increasingly incorporate on-device AI to enhance user experience with faster, personalized functionalities. Local AI processing not only improves privacy and responsiveness but also reduces energy consumption by limiting reliance on cloud computing. Constant innovation in consumer tech further supports the uptake of advanced edge AI chips, contributing approximately 1.0% annual market growth.
Autonomous Vehicles and Advanced Driver Assistance Systems as Growth Catalysts
Expanding use of autonomous vehicles and sophisticated driver assistance technologies acts as another major driver. Modern cars rely heavily on high-performance AI processors for real-time tasks like perception, navigation, and decision-making. Automotive companies are boosting investments in intelligent mobility solutions to improve safety and operational efficiency. The increasing rollout of connected and autonomous vehicle platforms sustains demand for advanced edge AI processors, adding an estimated 0.8% to annual market growth.
Key Market Opportunities Across Chip Types
Prominent growth opportunities in the edge AI chips space are anticipated within central processing units (CPUs), graphics processing units (GPUs), application-specific integrated circuits (ASICs), and field programmable gate arrays (FPGAs). Collectively, these chip types are projected to generate over $8.4 billion by 2030. This reflects rising deployment of AI-enabled edge devices, growing adoption of intelligent industrial automation, increasing need for high-performance, energy-efficient AI processing, and ongoing advancements in specialized semiconductor designs. This trend drives innovation in real-time AI computing and strengthens the global edge semiconductor ecosystem.
Individual chip markets are expected to expand as follows between 2025 and 2030: CPUs by $1 billion, GPUs by $3 billion, ASICs by $4 billion, and FPGAs by $0.4 billion. The market features a mix of large semiconductor manufacturers and niche AI processor developers. Companies focus on delivering high-performance AI acceleration, energy-efficient edge computing chips, advanced neural processing units, integrated heterogeneous chip solutions, and optimized hardware-software interoperability to meet the rising demand for real-time intelligence across connected devices. Emphasis on power efficiency, reduced latency, scalable AI workloads, secure processing at the edge, and diverse deployment compatibility remains crucial for maintaining competitive advantage.
NVIDIA Corporation as the Market Leader in Edge AI Chips
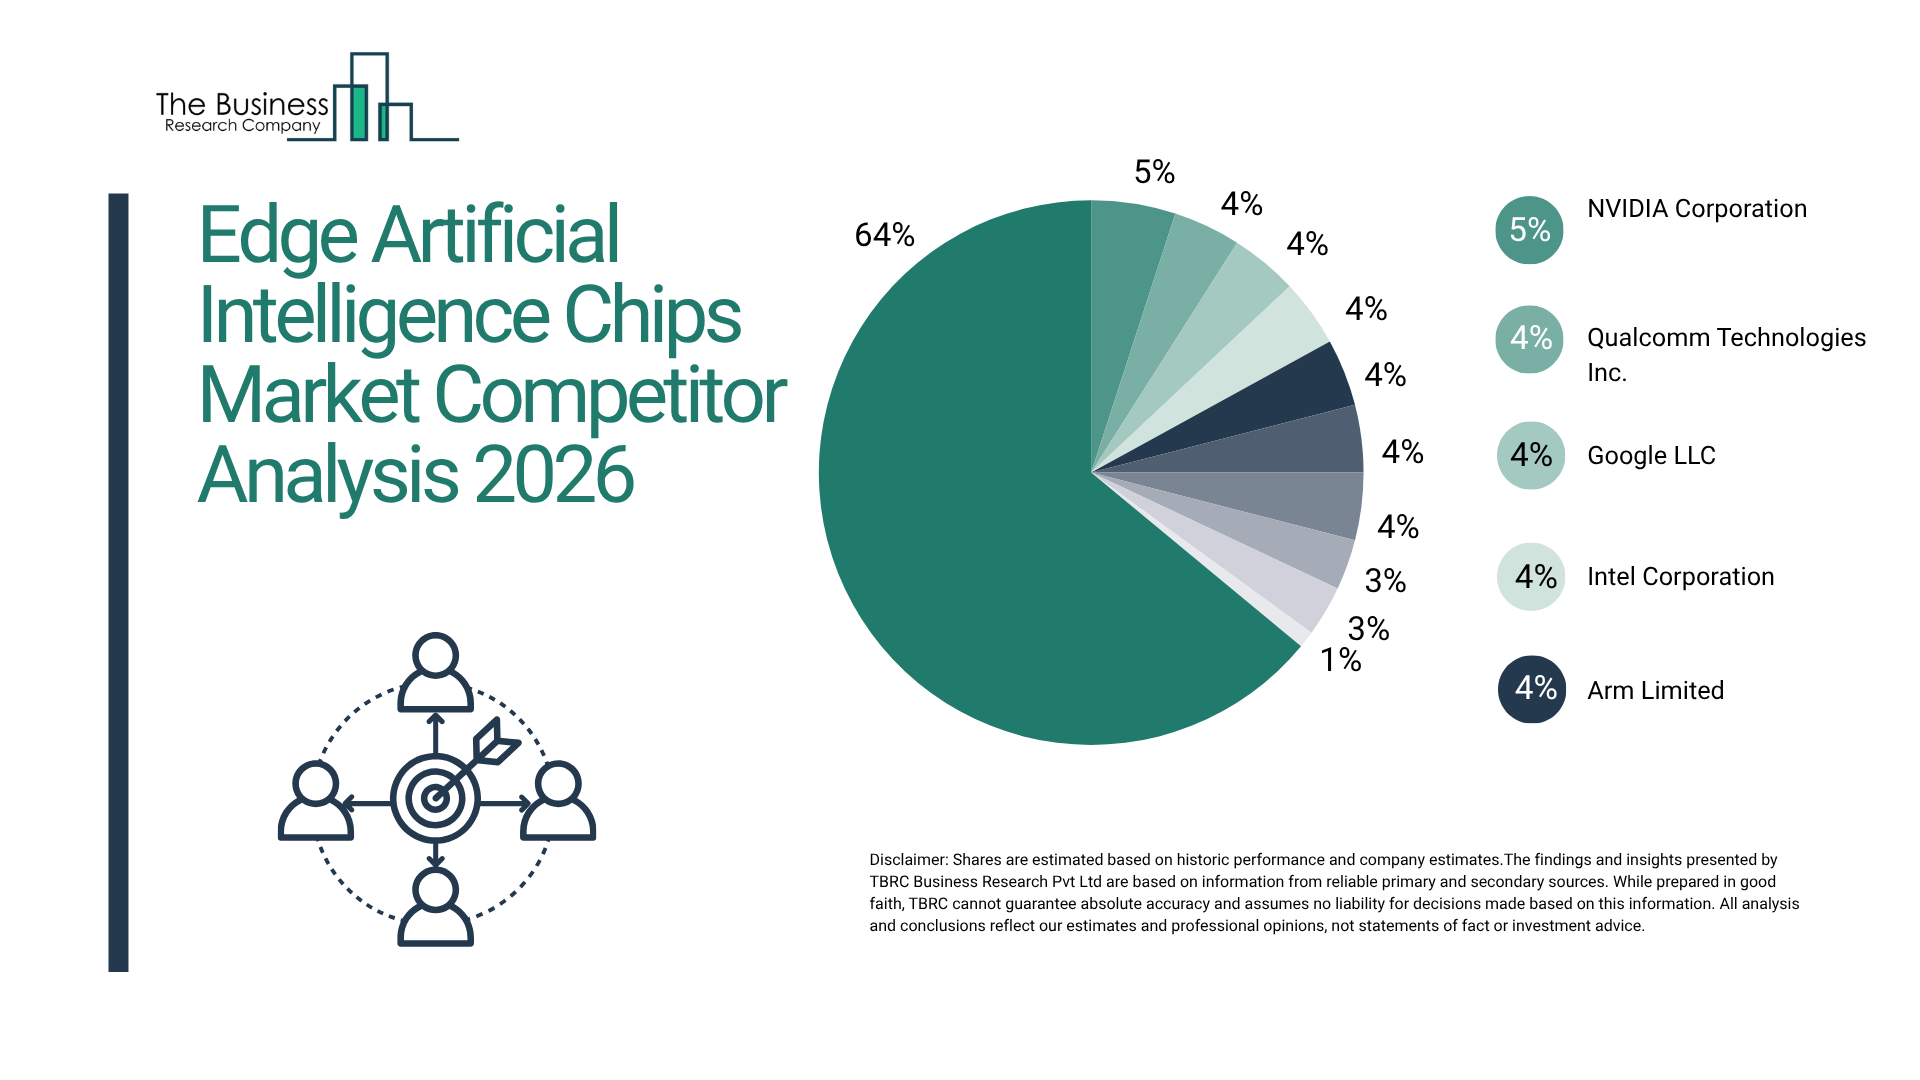
NVIDIA Corporation led global sales in the edge artificial intelligence chips market in 2025, capturing a 5% market share. Its extensive edge AI computing portfolio includes AI-enabled GPUs, embedded computing platforms, system-on-chip solutions, and edge inference processors. These products support real-time machine learning, intelligent automation, fast data processing, and scalable AI deployments across industries such as automotive, healthcare, smart cities, and industrial applications.
Prominent Market Players Shaping the Edge AI Chips Industry
Key participants in this market include NVIDIA Corporation, Qualcomm Technologies Inc., Google LLC, Intel Corporation, Arm Limited, MediaTek, Samsung Electronics Co. Ltd., Advanced Micro Devices Inc., Huawei Cloud Computing Technologies Co. Ltd., Hailo Technologies, Ambarella Inc., NXP Semiconductors, Renesas Electronics Co. Ltd., HiSilicon (Shanghai) Technologies Co. Ltd., Horizon Robotics, Cambricon Technologies Corp. Ltd., Texas Instruments Incorporated, Axera Semiconductor, Kneron, Syntiant, Mythic Inc., Cerebras Systems Inc., Innatera Nanosystems, Groq Inc., Graphcore Limited, MemryX, Blaize Inc., EdgeCortix Inc., Axelera AI, BrainChip Holdings Ltd., and Synaptics Incorporated.
Market Concentration and Competitive Landscape
The edge AI chips market exhibits moderate concentration; the top 10 companies accounted for 36% of total market revenue in 2025. Barriers to entry include advanced semiconductor manufacturing requirements, proprietary AI accelerator designs, increasing demand for powerful edge computing, and the necessity for optimized integration of hardware and software. Industry leaders like NVIDIA Corporation, Qualcomm Technologies Inc., Google LLC, Intel Corporation, Arm Limited, MediaTek, Samsung Electronics Co. Ltd., Advanced Micro Devices Inc., Huawei Cloud Computing Technologies Co. Ltd., and Hailo Technologies hold substantial market shares. They leverage diverse edge AI chip portfolios, strong ecosystem partnerships, global R&D capabilities, and continuous innovation focused on low-power AI processing, neural acceleration, and embedded computing platforms. As demand grows for intelligent edge devices, real-time AI inference, industrial automation, autonomous systems, and connected IoT applications, ongoing technological breakthroughs, collaborations, and next-gen chip development are expected to reinforce the dominance of these companies.
Leading Raw Material Suppliers Supporting the Edge AI Chips Market
Key suppliers of raw materials essential for edge AI chip manufacturing include TSMC, GlobalFoundries, United Microelectronics Corporation, Semiconductor Manufacturing International Corporation, SK hynix, Micron Technology, Kioxia Corporation, Winbond Electronics, ASE Technology Holding, Amkor Technology, Shin-Etsu Chemical, SUMCO Corporation, JSR Corporation, Tokyo Ohka Kogyo, BASF SE, Air Liquide, Entegris, DuPont, and Merck KGaA.
Primary Wholesalers and Distributors in the Edge AI Chips Supply Chain
Major wholesalers and distributors operating within the edge AI chips market encompass Arrow Electronics, Avnet, WPG Holdings, Future Electronics, Richardson Electronics, Macnica Holdings, Rutronik, Mouser Electronics, DigiKey, Farnell, RS Group, TME Electronic Components, EBV Elektronik, Premier Farnell, Marubun Corporation, Ryosan Company, Symmetry Electronics, Astute Group, and Heilind Electronics.
Key End Users Harnessing Edge AI Chips
Prominent end users of edge artificial intelligence chips include leading companies such as Tesla, Siemens AG, Robert Bosch GmbH, ABB Ltd., Honeywell International Inc., Schneider Electric SE, Cisco Systems Inc., Dell Technologies, Hewlett Packard Enterprise, Lenovo Group, Xiaomi Corporation, Sony Group Corporation, LG Electronics, Panasonic Corporation, DJI, Zebra Technologies, GE HealthCare, Philips, and Continental AG.
Competitive Trends Transforming the Edge AI Chips Market
Developer platforms for edge AI are revolutionizing the market by accelerating AI application development, simplifying deployment workflows, and enabling efficient on-device intelligence across various edge computing environments. For example, in January 2024, Ambarella Inc. launched its Cooper developer platform, which includes a preconfigured suite of hardware and software tools centered on its Cooper AI System-on-Chips (SoCs) and board-level hardware. This integrated development environment, optimized AI software stack, and hardware abstraction features streamline model deployment, enhance edge AI performance, and speed up the creation of intelligent edge devices across multiple applications.
Strategic Approaches of Companies to Maintain Market Leadership
To stay competitive, companies are focusing on energy-efficient AI accelerators that boost real-time edge computing performance, advanced neural processing units enabling low-latency intelligence on devices, and strategic partnerships that expand edge AI semiconductor ecosystems worldwide. Innovations continue to advance heterogeneous AI chip architectures and integration techniques, while adoption of edge AI chips is steadily growing across industrial and automotive sectors.
Our 2026 market reports now feature expanded strategic intelligence through market attractiveness scoring and analysis, total addressable market (TAM) analysis, company scoring matrix graphics and tables, Excel-based dashboards, market hotspots infographics, key technology and future trend analysis, along with updated graphics and tables.
Learn More About The Business Research Company
The Business Research Company (www.thebusinessresearchcompany.com) is a leading market intelligence firm renowned for its expertise in company, market, and consumer research. We have published over 30,000+ reports across 27 industries and 60+ geographies. Our research is powered by 1,500,000 datasets, extensive secondary research, and exclusive insights from interviews with industry leaders.
We provide continuous and custom research services, offering a range of specialized packages tailored to your needs, including Market Entry Research Package, Competitor Tracking Package, Supplier & Distributor Package and much more.
Disclaimer: Please note that the findings, conclusions and recommendations that TBRC Business Research Pvt Ltd delivers are based on information gathered in good faith from both primary and secondary sources, whose accuracy we are not always in a position to guarantee. As such TBRC Business Research Pvt Ltd can accept no liability whatever for actions taken based on any information that may subsequently prove to be incorrect. Analysis and findings included in TBRC reports and presentations are our estimates, opinions and are not intended as statements of fact or investment guidance.
Contact Us:
The Business Research Company
Americas +1 310-496-7795
Europe +44 7882 955267
Asia & Others +44 7882 955267 & +91 8897263534
Email: marketing@tbrc.info
Follow Us On:
LinkedIn: https://in.linkedin.com/company/the-business-research-company
Oliver Guirdham
The Business Research Company
+44 7882 955267
info@tbrc.info
Visit us on social media:
LinkedIn
Facebook
X
Legal Disclaimer:
EIN Presswire provides this news content “as is” without warranty of any kind. We do not accept any responsibility or liability
for the accuracy, content, images, videos, licenses, completeness, legality, or reliability of the information contained in this
article. If you have any complaints or copyright issues related to this article, kindly contact the author above.

Media gallery